By Ricardo Benítez, President, One Alliance Insurance Corporation
Puerto Rico does not need to be reminded what a natural disaster looks like. Hurricane María, the earthquakes of 2020 and Hurricane Fiona have all tested our homes, businesses, infrastructure and communities.
But these events have also taught us an important lesson about insurance: the moment that determines whether your insurance program truly responds is not the day the policy is purchased. It is the day you need to use it.
That is why preparing for the next event should include more than checking the generator, cistern and shutters. It should also include a conversation with your insurance producer and a careful review of your insurance program.
One of the most common concerns following a major loss is underinsurance. A home or commercial property insured several years ago may still carry limits based on construction costs that no longer reflect today’s reality. Materials, labor, equipment and other rebuilding expenses change over time. If the value of the property changes but the insurance limits do not, a policyholder may discover after a loss that the amount of insurance is not sufficient to rebuild or replace what was damaged.
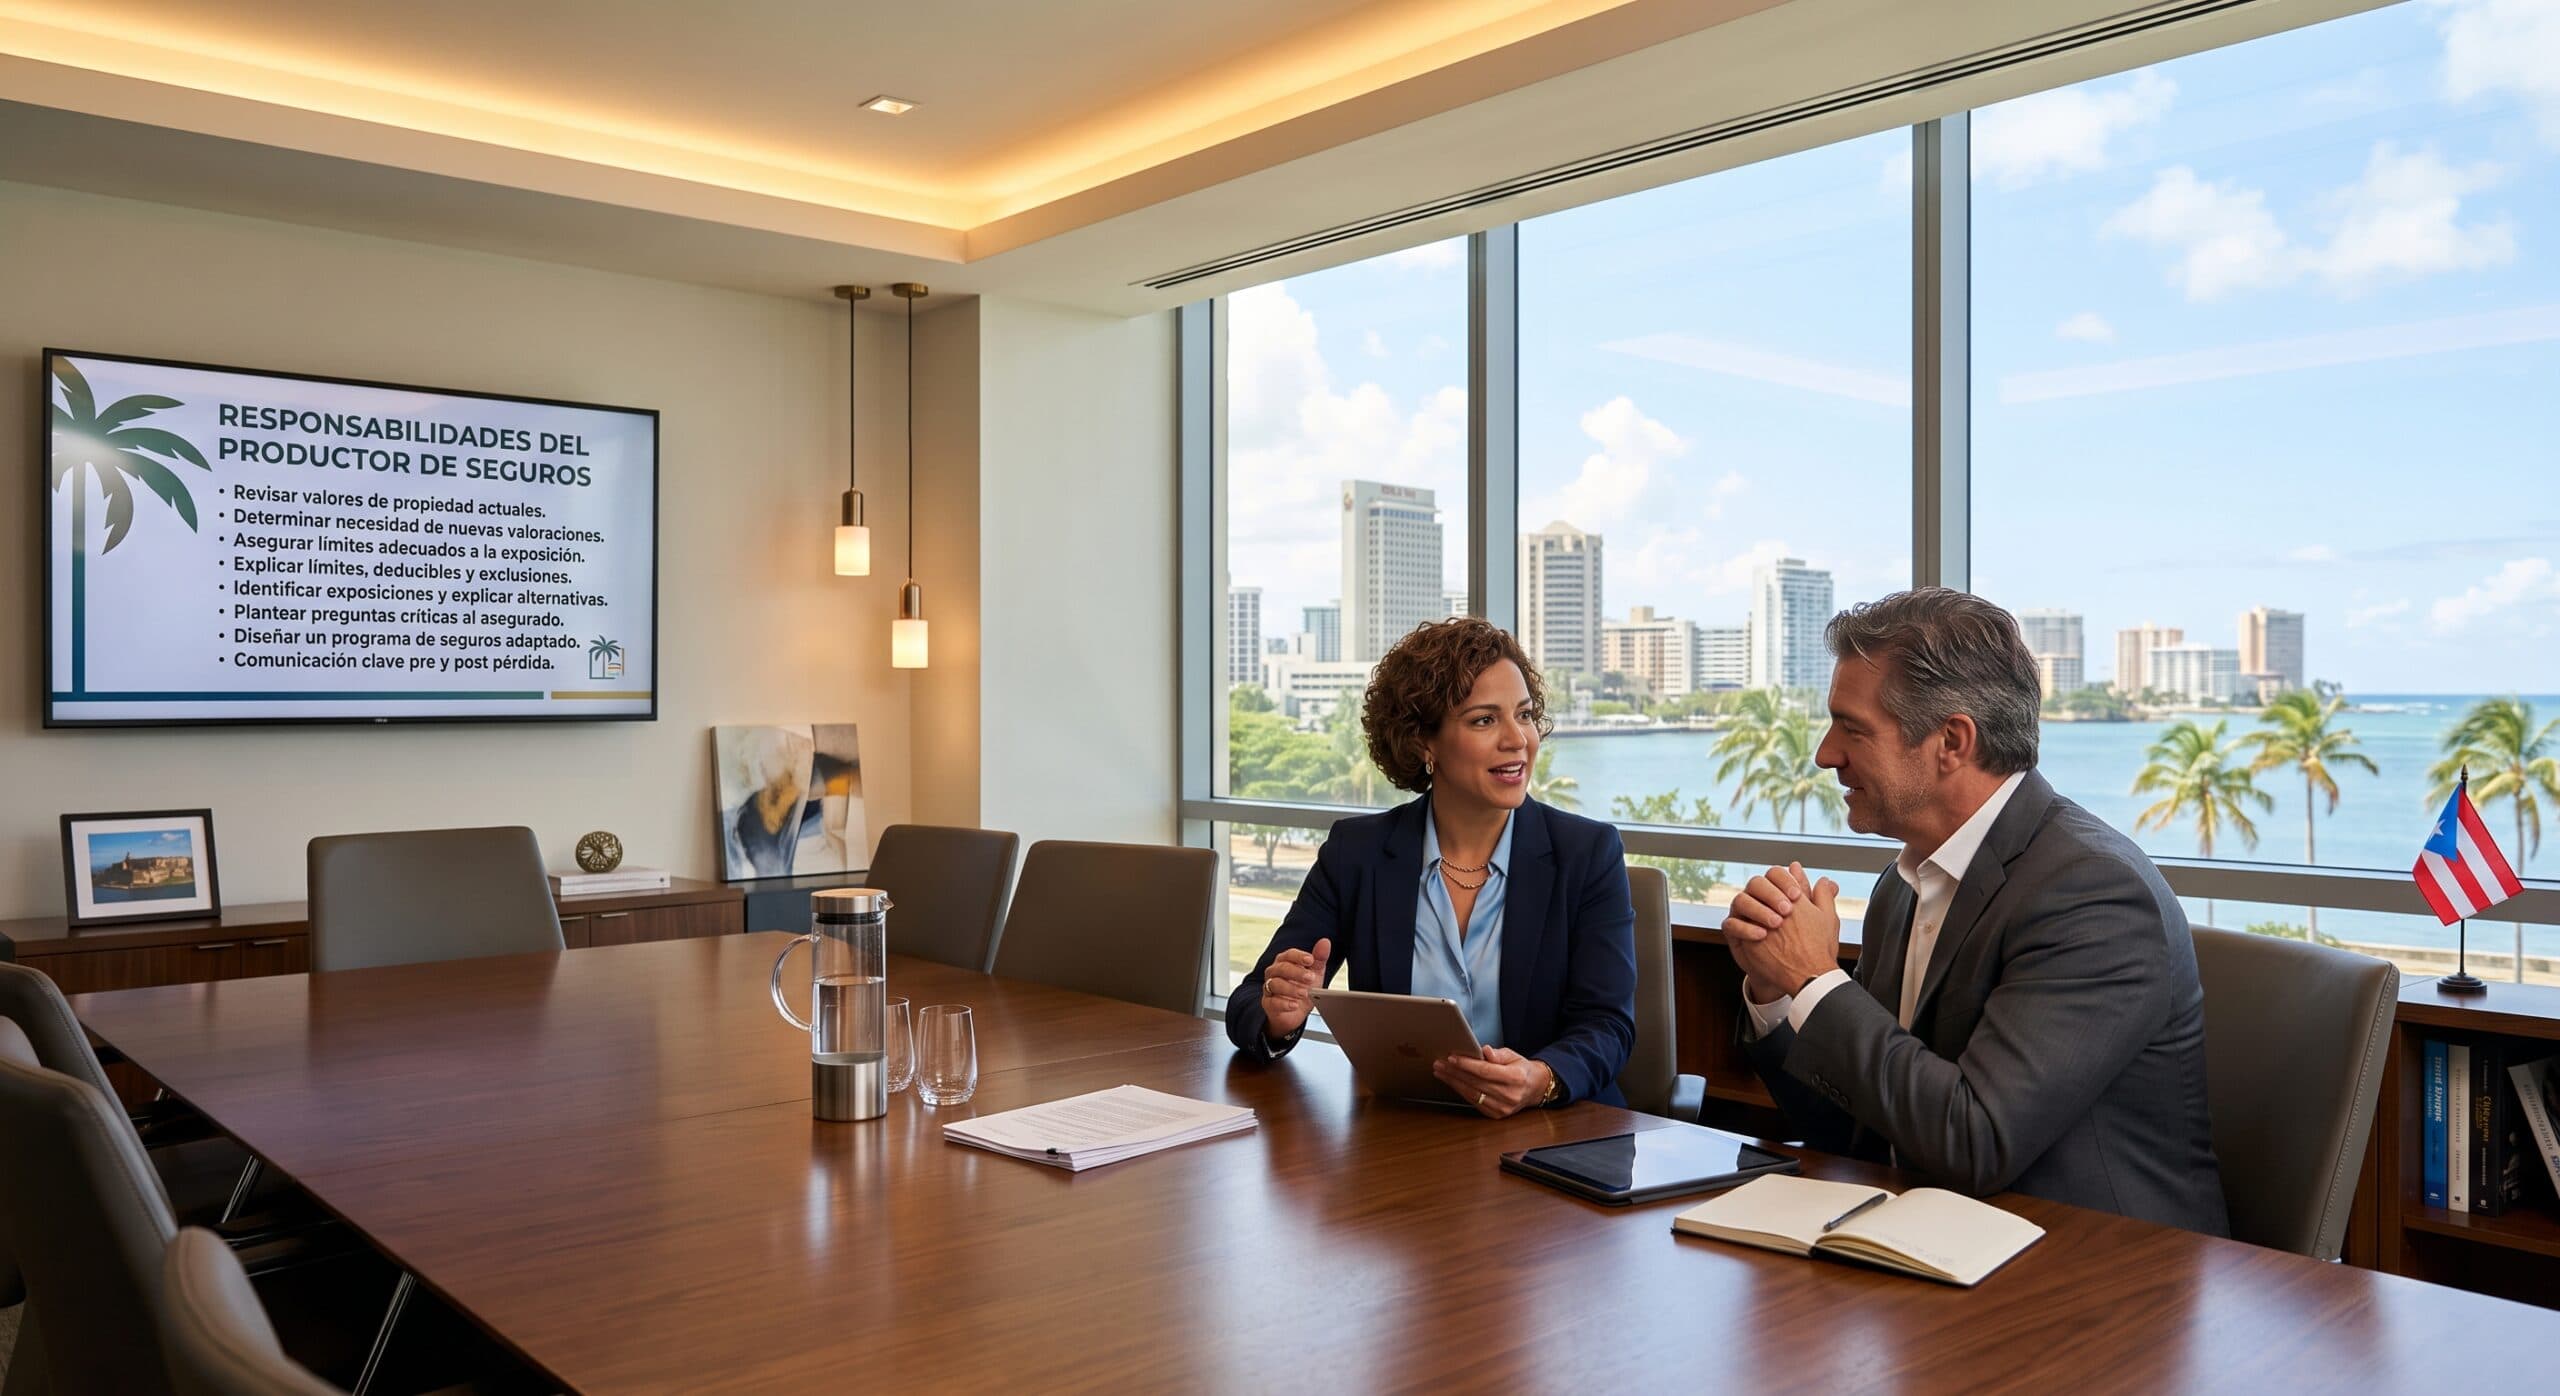
This is precisely where an experienced insurance producer can add value. Your producer can help you review current values, discuss whether updated valuations may be necessary and work with you to determine whether the limits on your policy continue to reflect your actual exposure.
Program to review with your insurance producer
Confirm that the values are current.
Understand your limits and deductibles.
Discuss important exclusions and additional coverages.
Review how a claim would be reported.
Make sure your producer understands any changes that have occurred in your home, business or operations.
The second issue is simply understanding what your policy covers and how it will respond.
Insurance policies contain limits, deductibles, exclusions, conditions and, in some cases, sub limits for particular types of losses. Flood, for example, may require separate coverage. Commercial policies may also involve business interruption, equipment, inventory and other exposures that deserve periodic review.
These details should not be discovered after a loss.
Ask your insurance producer to walk you through your insurance program. What are your limits? What deductibles apply? Are there important exclusions or limitations you should understand? Have your operations, property values or exposures changed since the policy was originally written?
There is no reason for a policyholder to go through this process alone.
Your insurance producer should be one of your most important resources. A good producer does more than obtain quotations or deliver a policy. The producer helps identify exposures, explains alternatives, raises questions that a policyholder may not know to ask and helps build an insurance program that reflects the client’s circumstances.
That relationship becomes especially important as businesses grow and personal assets change. A property renovation, new equipment, additional locations, higher inventory, changes in operations or significant increases in construction costs can all change an insured’s exposure.
Your insurance program should evolve with you.
There is another important question policyholders should ask: What happens when there is a claim?
Price will always be an important consideration when purchasing insurance, but it should not be the only consideration. The real value of an insurance policy becomes evident when something goes wrong.
How will the claim be reported? Who will assist you? What information should you have available? How quickly can the loss be evaluated? What can you do before an event to make the claims process easier afterward?
Here again, the insurance producer plays an important role. Producers understand their clients and can serve as an essential point of communication before, during and after a loss.
The best time to have these conversations is not when a hurricane is approaching Puerto Rico. It is during normal business conditions, when there is time to review the information, ask questions and make thoughtful decisions.
Before the next event, sit down with your insurance producer and review your program together.
Confirm that the values are current. Understand your limits and deductibles. Discuss important exclusions and additional coverages. Review how a claim would be reported. Make sure your producer understands any changes that have occurred in your home, business or operations.
Insurance can be complicated, but you do not have to navigate it alone.
Ask questions. Understand what you are buying. And most importantly, rely on the experience and advice of your insurance producer to help you make informed decisions.
Insurance is a promise made today about what will happen when something goes wrong tomorrow. A strong insurance program begins with understanding that promise before you ever need to test it.
The Puerto Rico brokerage is betting on specialized partnerships and personalized risk advisory rather than size to compete in an evolving insurance market
The 50-year-old firm’s integration into Grant Thornton Advisors, backed by New Mountain Capital, brings access to expanded expertise in AI, cybersecurity, and data analytics for island clients
The Puerto Rican insurance company maintains its A-rated financial strength while expanding capabilities to serve surety and property clients across the island’s economy