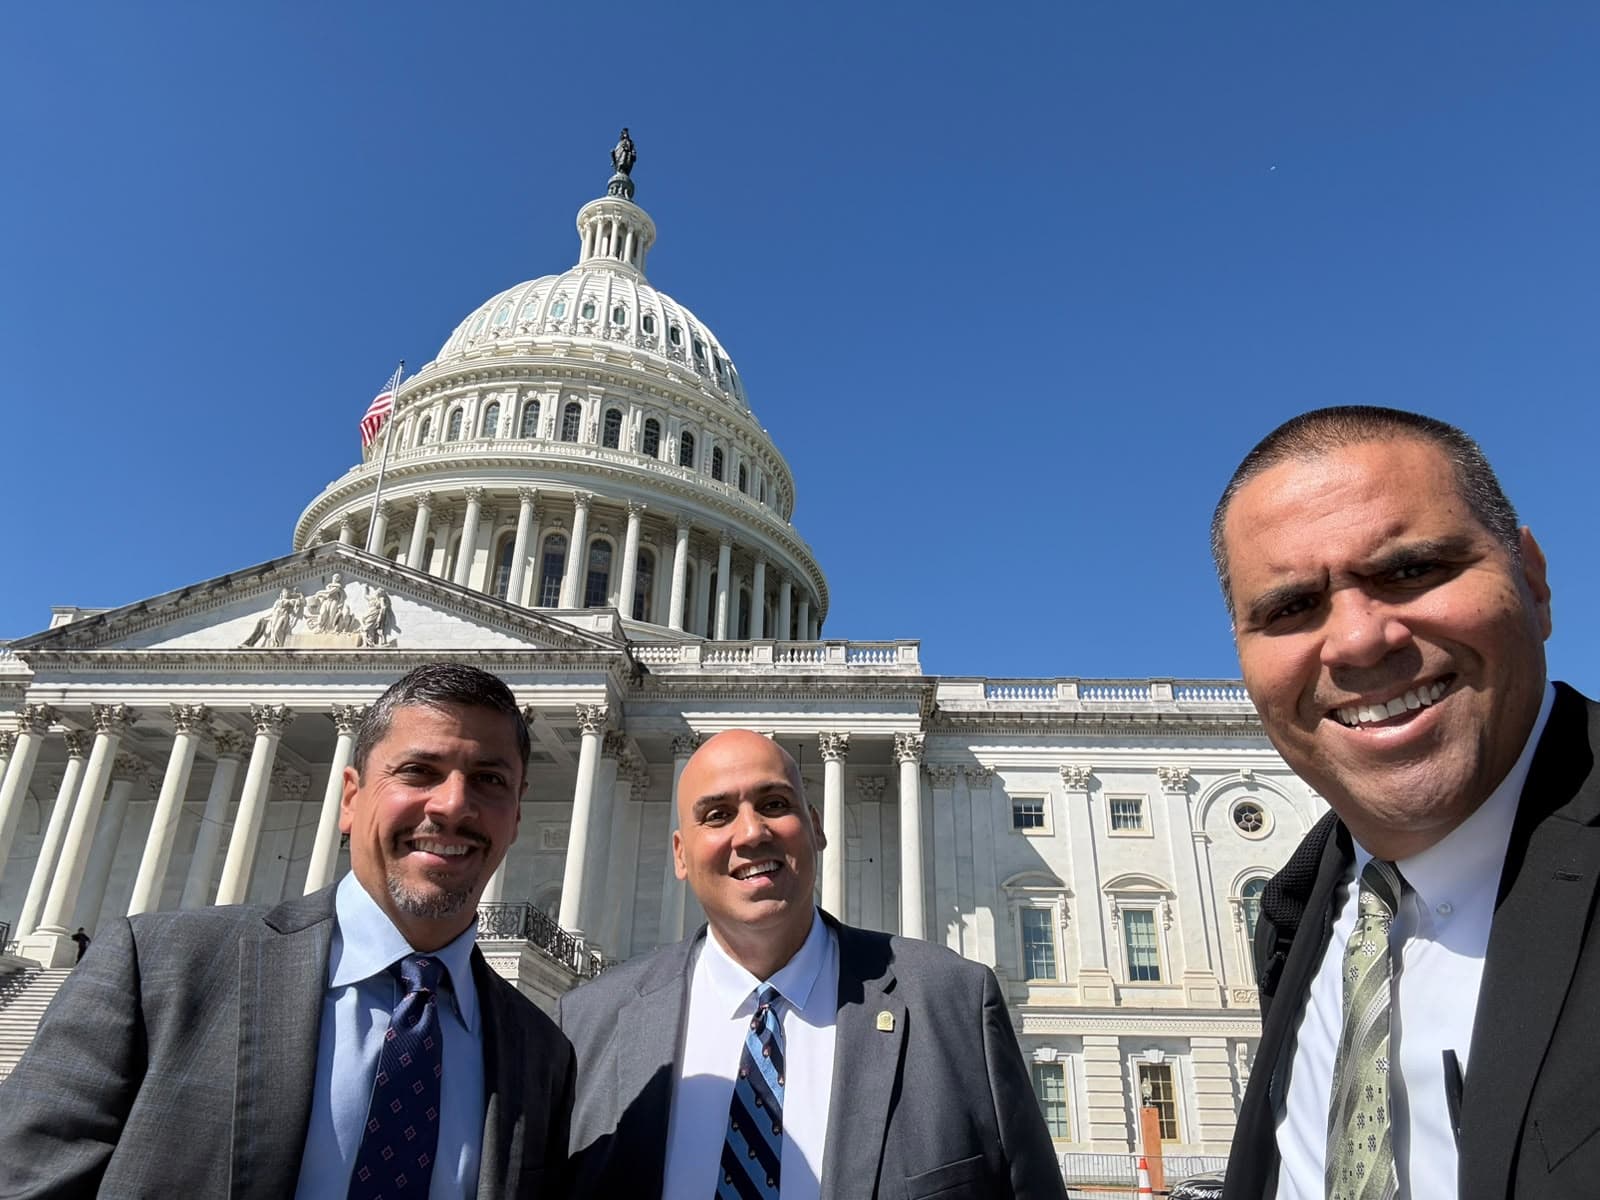
When José Acarón joined AARP Puerto Rico in 2004, the organization was already warning Congress that the nation’s Social Security program needed structural reinforcements. Two decades later, the alarm bells have grown much more urgent.
The program’s retirement trust fund is projected to deplete its reserves by 2032, triggering automatic benefit reductions to roughly 78% of current payments unless lawmakers in Congress intervene. For Puerto Rico, where Social Security is the primary income source for a majority of older adults and a stabilizing force in an economy marked by low wages and high poverty, the stakes are enormous.
More than 851,000 local residents receive Social Security benefits and 60% rely on them as their sole income. “Social Security is not in bankruptcy,” Acarón emphasized in an interview with Caribbean Business. “But if nothing is done, benefits will drop to 80% of what people receive now. That is the reality.”
His message is clear: the program is structurally sound but politically neglected. Puerto Rico, with its older population, lower labor-force participation rate, and higher disability rates, is uniquely vulnerable to the consequences.
“Social Security is the most successful federal program in U.S. history. It keeps people out of poverty. It keeps our economy afloat. We have to strengthen it, for this generation and the next.”
José Acarón, AARP Puerto Rico
The numbers illustrate the magnitude. In 2026, Social Security injected $12.8 billion into Puerto Rico’s economy. A 22% cut would slash that figure to roughly $10 billion, removing $2.6 billion in annual income from households that spend this money on local businesses. The average retired worker in Puerto Rico receives $1,315 a month. Under the projected cut, that would fall to $1,052—a loss of more than $260 monthly per beneficiary.
Disability beneficiaries would see their average payment drop from $1,434 to $1,147 a month.
“Social Security keeps over 251,000 older adults in Puerto Rico above the poverty line,” Acarón said. “Without it, nearly 70% of older adults would be living in poverty.”
The program’s stabilizing effect extends beyond individual households. Reduced benefits would mean lower consumer spending, higher demand for government assistance, and increased pressure on the Island’s already strained public finances. “If you cut Social Security, more people will need help from the government,” Acarón explained. “It becomes a vicious cycle.”
Direct Impact on Elderly Retirees
For retirees like Peggy Ann Bliss, an 80 year old writer living in an “égida,” or retirement home, the possibility of a cut is not an abstract policy debate; it is a direct threat to her survival. “[Social Security] is very important to me,” she said. “They don’t give us as much as we made (while working). No perks such as a car allowance.”
Bliss remembers years when cost of living adjustments (COLA) provided meaningful relief, but says recent increases of one or two percent barely register. COLA adjustments are made every year and the latest was 2.8% in 2026, keeping pace with the inflation rate of the previous year.
“We always wait to see how much it’s going to go up. I can’t afford to go anywhere except movies. I can’t afford shows. Can’t afford eating out. It’s $15 just to get a burger,” she said.
Her expenses do not match the assumptions built into federal policy. “The government assumes you don’t have certain expenses like a mortgage,” she said, “but I pay rent at my ‘égida.’” Despite her limited means, she does not qualify for housing subsidies because her income is considered high. “If you are poor, there are lots of cheap ‘égidas,’ but my Social Security check is too high to get a housing subsidy. It is not fair.”
Bliss buys clothing only on sale or secondhand. “I don’t buy much clothes now.”
Medical costs are another burden. “It’s $70 for eye drops and eye supplements not included in health insurance. Not really medicine—macular degeneration.” Even basic services strain her budget. “I can’t afford streaming. It’s $56 [a month] just for the cellphone. I can’t afford streaming or take a taxi.” She does her own hair to save money, though she still pays to have her nails done,” she said.
Emilia Rodríguez, another retiree, said that while she now has the time, she cannot afford to travel because her Social Security amount covers just her basic needs and “everything is going up, including utilities. I have to be watchful of my spending because even a small grocery shop is more than $60.”
Her story underscores the precarious reality facing thousands of older adults in Puerto Rico who depend on Social Security not only for basic needs, but also for dignity and stability. Any reduction would push many into crisis.
The financial sector is also beginning to take notice. Juan A. Villeta Trigo, president of the Puerto Rican Association of Financial Analysts, said the organization plans to examine Social Security and retirement issues more closely starting in 2027.
Congress is considering several bills that could reshape Social Security’s future. Some aim to strengthen the program; others propose procedural shortcuts that the AARP fears could lead to rushed or harmful changes.
Although the Association has not yet conducted a formal analysis, Villeta Trigo expressed concern about the economic pressures retirees face. “I worry about my wife, about myself and about my children—how parents are going to manage their retirement,” he told Caribbean Business at a recent event.
He believes cost-of-living adjustments should be more frequent and more substantial. “Inflation in Puerto Rico and the United States is rising. Even if they say it went down one month, over a year it’s above 3%. Budgets don’t stretch. There has to be some understanding to help retirees have more money available to spend.”
Villeta Trigo said he does not believe Social Security should be cut, noting that reductions would collide with rising consumer prices. “If milk is more expensive, cutting benefits is not practical,” he said.
Several Measures Before Congress
Meanwhile, Congress is considering several bills that could reshape Social Security’s future. Some aim to strengthen the program; others propose procedural shortcuts that the AARP fears could lead to rushed or harmful changes. The PROMISE Act, a bipartisan Senate bill, would force Congress to consider a long-term solvency package through a fast-track process. It would require the Social Security Administration to produce a detailed solvency report and trigger a mandatory legislative process whereby Congress must vote on a reform package with limited debate and amendments. The AARP opposes the measure. “This is too important to be decided behind closed doors,” Acarón said. “A small group should not be empowered to propose cuts without broad participation.”
A similar House bill, the Bipartisan Social Security Commission Act, would establish a 13-member commission tasked with proposing a solvency plan within a year. Congress would then vote on the plan under expedited procedures. The AARP opposes this bill as well, fearing it could produce a package that cannot be amended and might include benefit cuts or privatization elements. “This is a conversation that must include all sectors,” Acarón said. “Not a closed-door group.”
Other proposals take a different approach. The Strengthening Social Security Act of 2026, introduced by U.S. Rep. Linda Sánchez (Democrat from California), seeks to expand benefits and improve retirement security. Prior versions of the bill have included increasing the special minimum benefit, adjusting cost-of-living calculations to better reflect seniors’ expenses, and raising payroll taxes slightly for high earners. Acarón said he had not yet reviewed AARP’s national position on the measure but noted that the organization generally supports strengthening—not cutting—benefits.
Progressive lawmakers, including Senators Bernie Sanders (Independent from Vermont) and Elizabeth Warren (Democrat from Massachusetts), have proposed eliminating the payroll tax cap, which currently limits Social Security payroll taxes to the first $184,500 of wage income. Removing the cap would significantly increase revenues without affecting most Puerto Rican workers, whose wages fall well below the threshold. “There is no silver bullet,” Acarón said. “It has to be a combination of seven or eight measures.”
Other ideas circulating in Congress include raising the retirement age, adjusting cost-of-living formulas, and means-testing benefits for wealthy retirees. The last time Congress increased the full retirement age was 1983, when it was upped by two years from 65 to 67 years old. Means testing is a methodology that uses a formula, based on someone’s income or assets, to determine eligibility. This could mean reducing or eliminating Social Security benefits for retirees with high incomes or assets.
Acarón stresses that all options must be evaluated together, not in isolation. Raising the retirement age, for example, could disproportionately harm low-income workers and those in physically demanding jobs—categories that are common in Puerto Rico. Modifying COLA downward would erode purchasing power in an Island where the cost of living has risen sharply. Means-testing benefits would have minimal direct impact in Puerto Rico since so many retirees are low income, but could set a precedent for broader cuts.
Despite years of warnings, Congress has not advanced a solvency package. Acarón attributes the paralysis to political division and fear of voter backlash. “There is no environment right now to take measures,” he said. “These are decisions with political cost, and Congress keeps kicking the can down the road.” He worries that waiting until the last minute will force lawmakers into rushed, poorly designed reforms. “If they wait, the measures will be harsher.”
AARP Puerto Rico’s Proactive Approach
While federal action remains uncertain, AARP Puerto Rico is pushing for local measures to help workers build supplemental retirement savings. The organization is backing legislation to create a retirement savings instrument for small business employees, gig workers and self-employed individuals—groups that typically lack access to employer-sponsored plans. “There is a bill already filed,” Acarón said. “It would create a financial tool so people can save throughout their lives.”
The initiative is part of a broader effort to improve financial literacy on the Island, where many workers struggle to save due to low wages and high living costs. “Financial education is a major weakness in Puerto Rico,” he said. “We need to teach people from a young age how to plan for retirement.”
AARP Puerto Rico has begun mobilizing its membership through educational events, email campaigns and outreach to federal officials. But Puerto Rico faces a structural disadvantage: its sole representative in Congress cannot vote. “That limits our influence,” Acarón acknowledged. “But [the resident commissioner] understands the importance of Social Security and is aligned with our position.”
AARP expects mobilization to intensify as the trust fund deadline approaches. “When the media starts paying attention, the public will too,” Acarón said. “Right now, there are too many distractions.”
The future of Social Security is not just a policy debate—it is a political flashpoint. Older Americans vote at higher rates than any other demographic and they will be the most affected by benefit cuts. Acarón believes this dynamic could force Congress to act. “This will create a political debacle,” he said. “There is a cost to doing nothing.”
For Puerto Rico, the consequences of inaction would be severe: deeper poverty, reduced consumer spending, higher demand for public assistance, and a weakened economy. For retirees like Bliss, the consequences would be personal and immediate. “I can’t afford a cut,” she said. “I can’t afford much of anything now.”
Acarón’s final message is simple. “Social Security is the most successful federal program in U.S. history. It keeps people out of poverty. It keeps our economy afloat. We have to strengthen it, for this generation and the next.”