Bondholders challenge revenue calculations and $1.45 billion in spending.
The Financial Oversight and Management Board (FOMB) has asked the federal Title III court overseeing the Puerto Rico Electric Power Authority’s (PREPA) bankruptcy to reject efforts by bondholders to exclude testimony from two of its principal expert witnesses, arguing that both experts relied on accepted methodologies and analyzed years of financial and operational records to address disputes central to the bondholders’ claims.
In separate filings submitted Nov. 3, the FOMB opposed motions challenging the testimony of accountants and utility experts David Plastino and David Daly, whose analyses support the board’s position in the long-running fight over PREPA revenues, expenses, and the scope of bondholders’ liens under PROMESA.
The evidentiary dispute is unfolding within a broader accounting counterclaim filed by PREPA bondholders, which seeks a judicial determination on how revenues and expenses should be calculated under PREPA’s Trust Agreement and the Bankruptcy Code.
The first filing concerns David Plastino, an accounting expert retained to calculate PREPA’s “Available Net Revenues” from July 2017 through June 2025 under legal assumptions advanced by the Oversight Board. According to the filing, Plastino analyzed PREPA’s financial records, reconciled audited financial statements and other accounting data, and calculated the consequences of competing interpretations of PREPA’s Trust Agreement and Section 928 of the Bankruptcy Code.
Bondholders argue Plastino’s methodology should be excluded because it relies on legal instructions from counsel and departs from generally accepted accounting principles. The Oversight Board counters that the challenge is really an attempt to attack its legal interpretation of the Trust Agreement rather than Plastino’s accounting work. It argues experts are routinely permitted to apply legal assumptions supplied by attorneys and then evaluate the resulting financial impact.
Historical records do not paint accurate picture of PREPA’s revenues
The filing highlights one of Plastino’s most significant findings: that updating PREPA’s historical monthly operating reports with final audited balances and correcting omissions would reduce what had been reported as approximately $3.7 billion in net revenues between fiscal years 2018 and 2023 to an estimated $1.1 billion deficit. The Oversight Board says that result demonstrates why historical reports alone cannot resolve the dispute over PREPA’s revenues and expenses.
The second filing focuses on utility industry veteran David Daly, whom the bondholders seek to bar from testifying about whether roughly $1.45 billion in PREPA expenditures after the bankruptcy filing were reasonable and necessary.
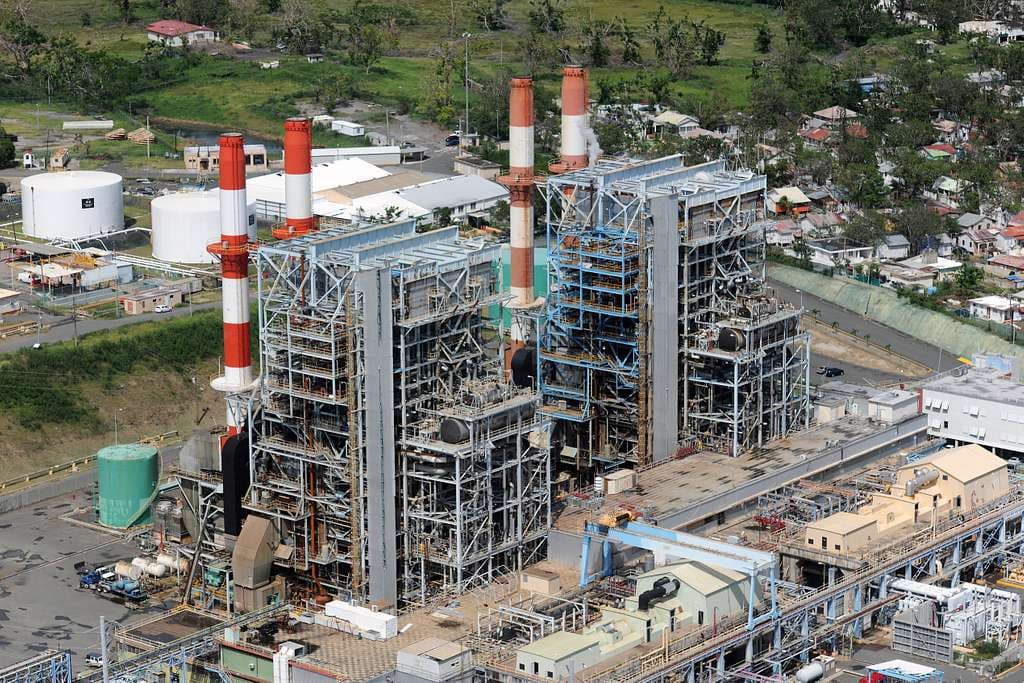
Daly, a former executive with Public Service Enterprise Group, concluded that approximately $1.45 billion in non-federally funded spending during fiscal years 2018 through 2025 was necessary to address severe deterioration throughout PREPA’s transmission, distribution and generation systems. He further concluded that even when combined with federal disaster funding, the investment was insufficient to resolve longstanding deficiencies in Puerto Rico’s electric grid.
According to the Oversight Board, Daly reviewed engineering studies, condition assessments, regulatory orders, spending records and other operational documents. He found that PREPA entered the bankruptcy period with a severely degraded system that was further damaged by Hurricanes Irma and Maria, earthquakes, and years of deferred maintenance.
Bondholders say testimonies rely on flawed assumptions
The filing states that Daly evaluated approximately 74% of the expenditures in detail, representing about $1.08 billion in spending, and concluded the funds were directed toward repairing and maintaining critical infrastructure. He found that the remaining expenditures also met the same necessity standard after individual review.
FOMB argues that bondholders are improperly attempting to transform disagreements over Daly’s conclusions into challenges to admissibility. The board notes that Daly did not offer legal opinions regarding whether expenditures constitute “Current Expenses” under the Trust Agreement or “necessary operating expenses” under federal bankruptcy law, but instead evaluated whether the spending addressed documented operational needs.
The Oversight Board also points to findings by the Puerto Rico Energy Bureau, which previously concluded PREPA lacked access to capital markets and therefore required ratepayer-funded investment to maintain and repair its system. According to the filing, the regulator repeatedly determined that major infrastructure projects remained necessary even when it directed that some be funded through federal assistance rather than customer rates.
The Oversight Board argues the experts’ analyses will help the court understand the practical financial consequences of competing legal interpretations, while bondholders contend the testimony relies on flawed assumptions and should be excluded.
The court has not yet ruled on either motion.