Local Economy Holding Steady, Not Accelerating, New Congress Could Decide What Comes Next
September’s activity index rose 0.8% from a year earlier, a better reading than the Oversight Board’s nine-month report, but the Medicaid cliff and Washington’s new balance of power will matter more than any single month
Puerto Rico’s Economic Activity Index reached 129.4 points in September, up 0.6% from August and 0.8% from September 2025, the Department of Economic Development and Commerce (DDEC) reported today. Gov. Jenniffer González Colón said the results “reflect signs of stability in our economy.”
Set against the Financial Oversight and Management Board’s October report, which found the same index down 0.2% over the first nine months of fiscal 2026, the new reading is an improvement. It is not, however, a break from the pattern of slow growth the board described: a year-over-year gain under 1% is consistent with real gross national product growth of about 0.4%.
The more consequential news for the island’s economy arrived in Washington overnight. Democrats won control of both chambers of Congress in the midterm elections, which changes the odds on the federal decisions, starting with Medicaid, that will shape Puerto Rico’s growth through 2028.
September’s index says the economy is not deteriorating. The board’s report says that stability depends on federal funds that will eventually run out, and the election gives the island better odds of extending the most important of them. Businesses should plan on slow growth through 2027 and treat the Medicaid decision, after the new Congress convenes, as the event most likely to move the forecast in either direction.
What the September index says
The index tracks four indicators: payroll employment, electricity generation, gasoline consumption and cement sales. Compared with September 2025, three rose. Nonfarm payroll employment grew 0.8% to 956,200 jobs, roughly 7,600 more than a year earlier. Electricity generation rose 2.1% to 1,546.7 million kilowatt-hours, and cement sales rose 2.2% to 1.29 million 94-pound sacks. Gasoline consumption fell 1.0% to a preliminary 74.7 million gallons.
In the monthly reading, payroll employment fell 0.7% from August and electricity generation fell 2.5%. Cement sales were unchanged, and gasoline consumption, up 3.3%, was the only component to rise. The index’s month-to-month gain was carried by the one component that moved in the opposite direction from the others on an annual basis.
DDEC Secretary Carlos J. Ríos Pierluisi cautioned that the index “does not directly measure changes in the general price level.” That limits what readers should take from the headline. The index is a coincident indicator that correlates highly with real gross national product but is not a monthly estimate of it, and it counts activity, not purchasing power. A household paying more for groceries and power can generate the same gasoline sales and payroll as before while feeling poorer.
How it fits with the Oversight Board’s warning
The board’s October report described “slower, more measured growth rather than a downturn,” citing labor shortages, slow deployment of federal funds and weak labor force participation. September’s numbers fit that description more than they contradict it. Employment is up, but by less than 1%, in an economy where manufacturers told CB this fall that a shrinking workforce is the main obstacle to expansion.
Cement sales offer the clearest cross-check. CB reported in August that cement sales for fiscal 2026 rose about 1.2%, to roughly 15.4 million sacks. September’s 2.2% annual gain, to 1.29 million sacks, suggests construction activity is firming slightly, which matches the board’s observation that federal reconstruction money is still flowing. Federal programs have disbursed roughly $62.2 billion since fiscal 2018, and another $56.2 billion remains to be deployed.
That is the board’s central caution: the money may be masking structural weaknesses. If so, a steady index is partly a measure of how much federal support is arriving, not of how strongly the private economy is expanding.
The 1.0% drop in gasoline consumption, a rough proxy for consumer activity, points in the same direction, and the board’s list of risks, which includes tariffs and rising health costs, has not shortened.
A reading for business owners
For planning purposes, the data support a base case of flat to slightly rising demand, not a downturn and not a boom. Businesses tied to construction, utilities and public contracts are seeing steadier conditions than those that depend on discretionary consumer spending, where the gasoline reading and the monthly payroll decline suggest caution.
Owners should also separate the statistical story from the cost story. With activity growing less than 1% and prices not captured by the index, small and midsize firms facing higher energy and labor costs may see little relief in their margins even if the index keeps edging up. That is the pressure behind what CB has called the Pymes Power Cliff.
The indicators worth watching over the next two quarters are the next index releases, to see whether September’s annual gain holds beyond one month; payroll employment, where the August to September decline needs to reverse; and the board’s next quarterly report, which will update its fiscal projections. A second consecutive monthly decline in jobs would weaken the case for stability.
The new Congress enters the picture
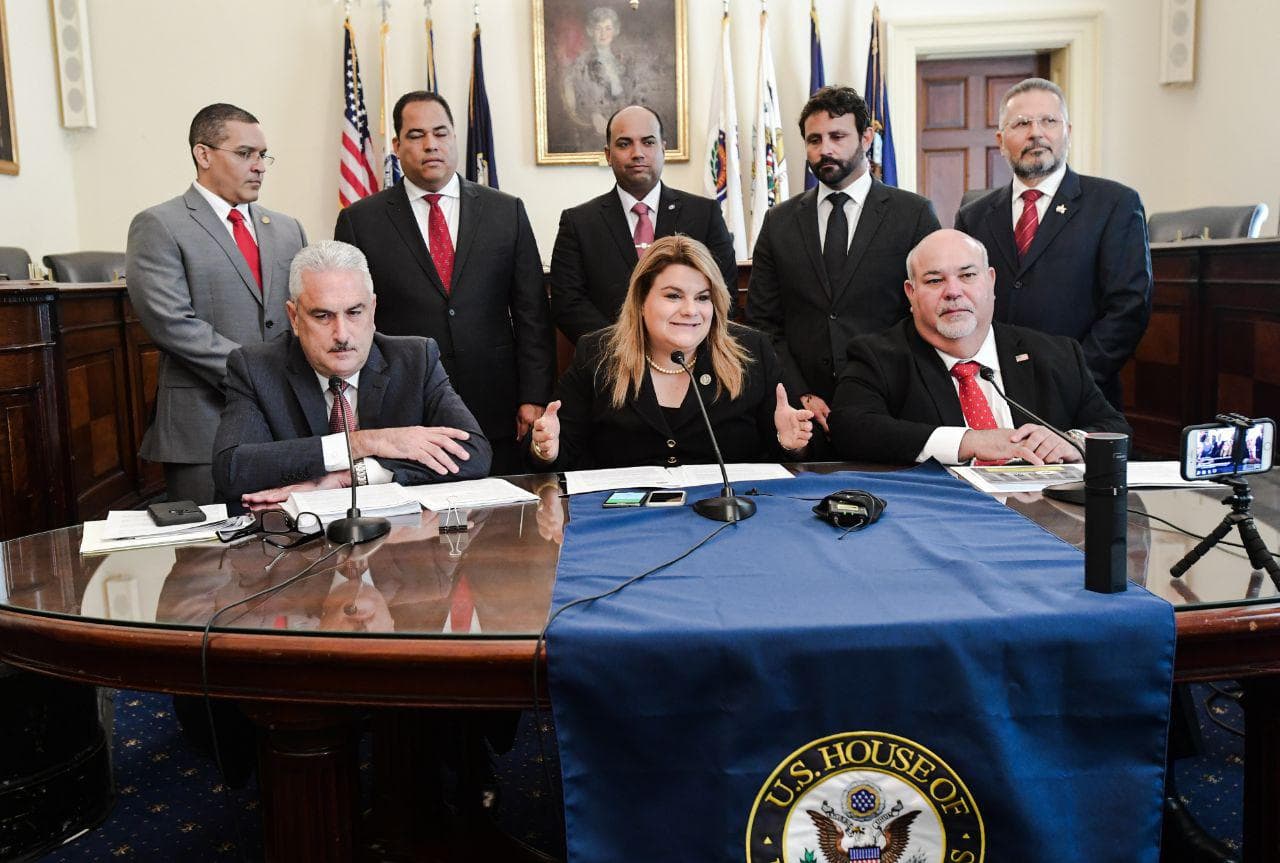
The new Congress takes office in January for the last two years of President Donald Trump’s term. Resident Commissioner Pablo José Hernández, the Popular Democratic Party president who caucuses with Democrats, said Puerto Rico “will benefit from having a friend like Hakeem Jeffries” as House Speaker and from Sen. Chuck Schumer as Senate majority leader, according to Metro Puerto Rico, a Caribbean Business sister newspaper. “We wake up with hope,” he said.
The party’s secretary general, Manuel Calderón Cerame, also told Metro that the result gives Hernández a better chance to defend Medicaid funds and advance water, energy and reconstruction projects. Metro noted that any legislation will still require agreement between Congress and the White House, which limits what a Democratic majority can deliver alone.
A president who can veto bills and a Senate where most legislation needs 60 votes mean Democrats can shape the agenda and block initiatives more easily than they can enact their own. For Puerto Rico, the realistic gains are in what must pass anyway, such as funding bills, and in oversight of how existing federal money is spent.
Medicaid is the first test
Puerto Rico’s Medicaid funding is scheduled to fall from about $4.2 billion a year to roughly $500 million when current funding ends on Sept. 30, 2027. According to published reports, a multisectoral committee commissioned by La Fortaleza asked this fall for a new allocation of $4.815 billion a year and warned that at least 860,000 people could lose coverage without it. Medicaid pays for about four-fifths of the medical services used by 40% of the population.
The Oversight Board has put the budget exposure from maintaining current services at up to $3.8 billion a year from fiscal 2028 through 2030, and projects deficits above $1 billion annually from fiscal 2029. A Medicaid cliff is therefore not only a health-care problem. It is the largest single fiscal risk facing the island’s finances and, through hospitals, clinics and the Plan Vital that serves about 47% of the population, a large share of local employment.
A Democratic House improves the odds that a reauthorization is scheduled and treated as a priority, particularly as Hernández had already said he expected the debate to run into 2027. It does not guarantee the full $4.8 billion, because the island’s request competes with other states’ health priorities and the Republican president retains a veto. What the election changes is the leverage: Puerto Rico will negotiate with a Congress led by allies, not with one led by its opponents.
Other federal levers, and their limits
Beyond Medicaid, the new majority gives Puerto Rico a chance to revisit proposals that failed under Republican control.
Hernández said earlier this year that a setback in efforts to move the island’s nutrition block grant to the national SNAP program “does not mean that this measure is permanently defeated.”
Democrats in the House have also introduced legislation to restore fiscal authority to the island’s elected government, though it faces long odds while the White House remains in Republican hands.
Tariffs, which the board lists among the risks to its fiscal projections, are a harder case. Many of the current duties were imposed by executive action, which Congress can challenge but cannot easily reverse over a veto.
Democratic candidates ran on addressing tariffs and lowering costs, and Calderón read the result as a rejection of the administration’s tariff policy, but the practical effect on an economy that imports most of its inputs will depend on what the White House does, not on the vote count.
The picture for Puerto Rico is therefore one of steady footing and uncertain footing ahead. September’s index says the economy is not deteriorating. The board’s report says that stability depends on federal funds that will eventually run out, and the election gives the island better odds of extending the most important of them. Businesses should plan on slow growth through 2027 and treat the Medicaid decision, expected sometime after the new Congress convenes, as the event most likely to move the forecast in either direction.